Elon sits on both sides. Tesla is already long SpaceX. The only collar that holds up in court is an independent Tesla committee.
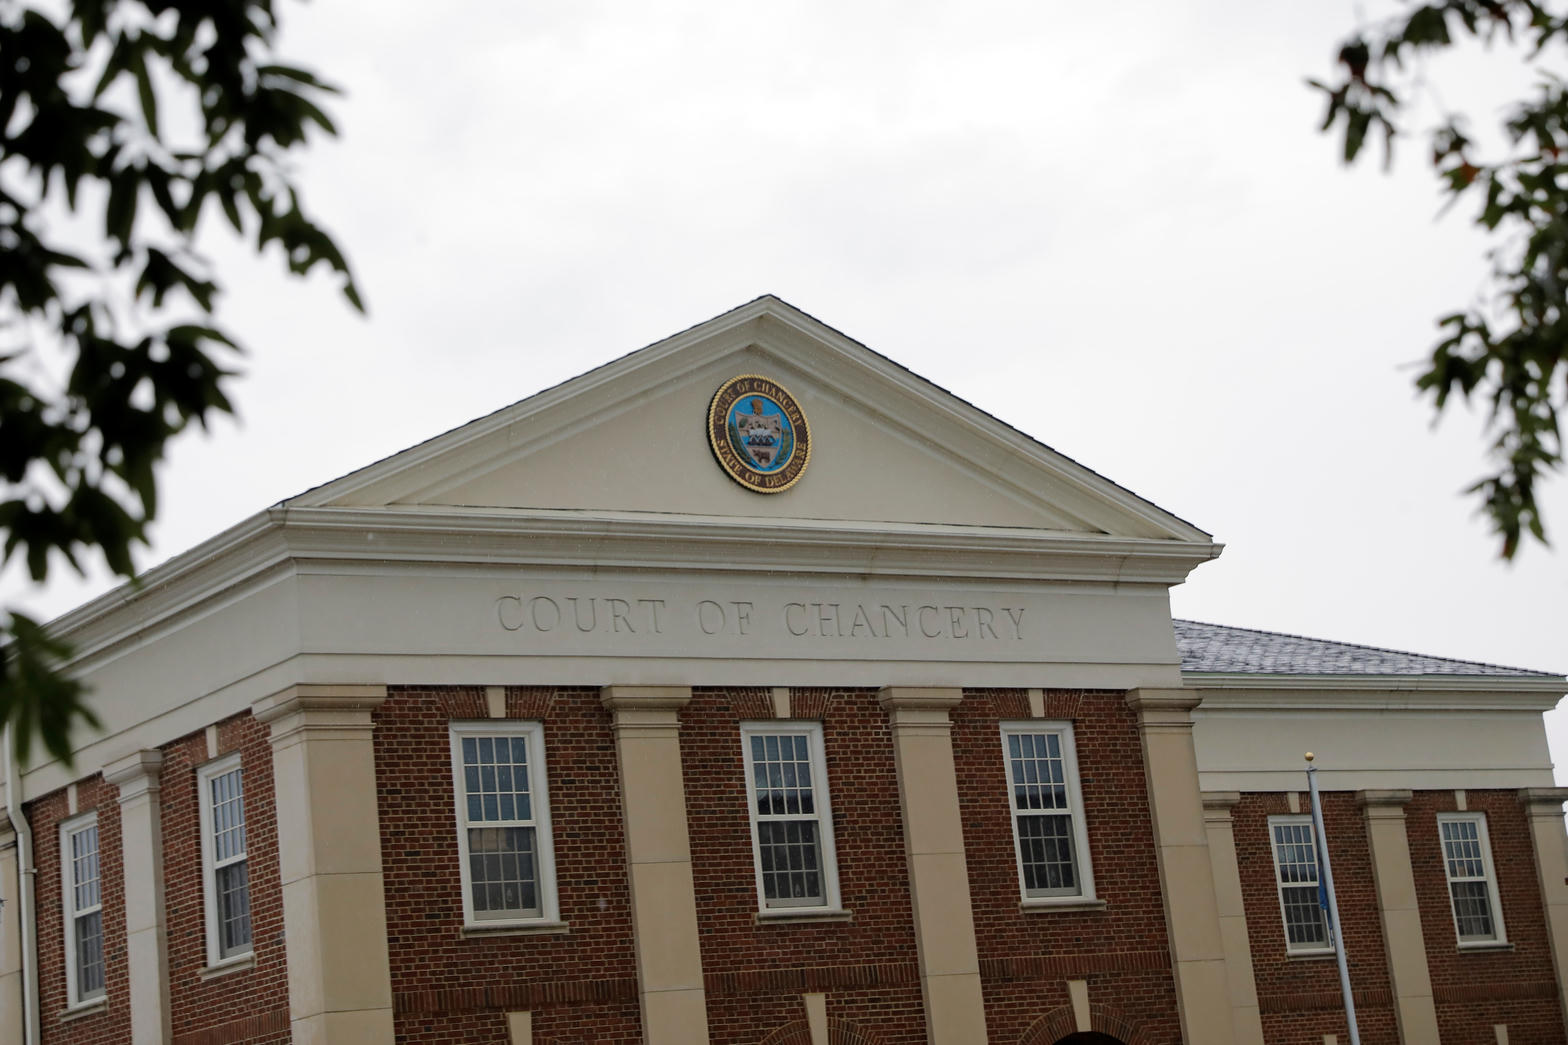
Delaware Court of Chancery — already voided one Tesla pay package. Agency problems live here.
Elon on both sides
~13–20% Tesla economic / ~20% votes; SpaceX voting control ~84% post-IPO. He is buyer and seller.
He is the controlling mind of the buyer (Tesla) and the seller (SpaceX). ~13–20% Tesla economic interest and ~20% of votes, options-dependent; SpaceX voting control described ~84% post-IPO. A merger is a related-party sale of one of his companies to the other. Delaware — and now Texas — fiduciary law treats that as the highest-scrutiny class, not a handshake. Combining them “might make Elon’s life a little easier.” That is the honest executive reason, not a fairness opinion.
Who pays
Tesla minority holders if the exchange ratio overpays for SpaceX. SpaceX employees and early holders if Tesla’s multiple is the one that gets haircut. Elon is long both sides.
Tesla’s SpaceX stake
Q2 2026 Tesla booked a $1B mark-to-market gain on SpaceX holdings. Tesla is already long the other side of the merger.
Tesla’s P&L already moves with SpaceX’s mark. A merger is then Tesla buying more of an asset it already owns, with the CEO on both cap tables. Fairness opinions have to net this out. A slide that ignores the existing stake is not a fairness opinion — it is a double count dressed as synergy. The $1B MTM is the receipt.
Who pays
Tesla holders if the stake is double-counted into the exchange ratio. SpaceX if “we already own some” is used to justify a skinny collar.
Framework agreement
Deepened relationship via investment + framework. Projects still “subject to separate negotiations.”
The companies “deepened the relationship” via investment plus a framework. Projects remain “subject to separate negotiations.” That phrase is the tell: no transfer-pricing schedule a Tesla minority holder can audit, no committed capex line, no offtake. It is a permission slip to keep talking — including about Terafab. A framework is not a merger, not a foundry contract, and not arm’s length.
Who pays
Whichever P&L silently funds the shared shop until a committee prices it.
xAI inside SpaceX
Collapsed pre-IPO. Grok-in-cars is then a related-party AI supply into Tesla, not a third public company.
xAI collapsed into SpaceX pre-IPO. Grok-in-cars is then a related-party AI supply into Tesla from a company Elon also controls, not a third public counterparty. Tesla’s inference stack and SpaceX’s satellite AI share a vendor that is not arm’s length. A merger would collapse the file. Staying separate keeps a transfer-pricing fight forever — Tesla holders paying SpaceX/xAI prices for in-car AI.
Who pays
Tesla holders paying related-party prices for in-car AI. SpaceX holders if Tesla is the only scaled customer.
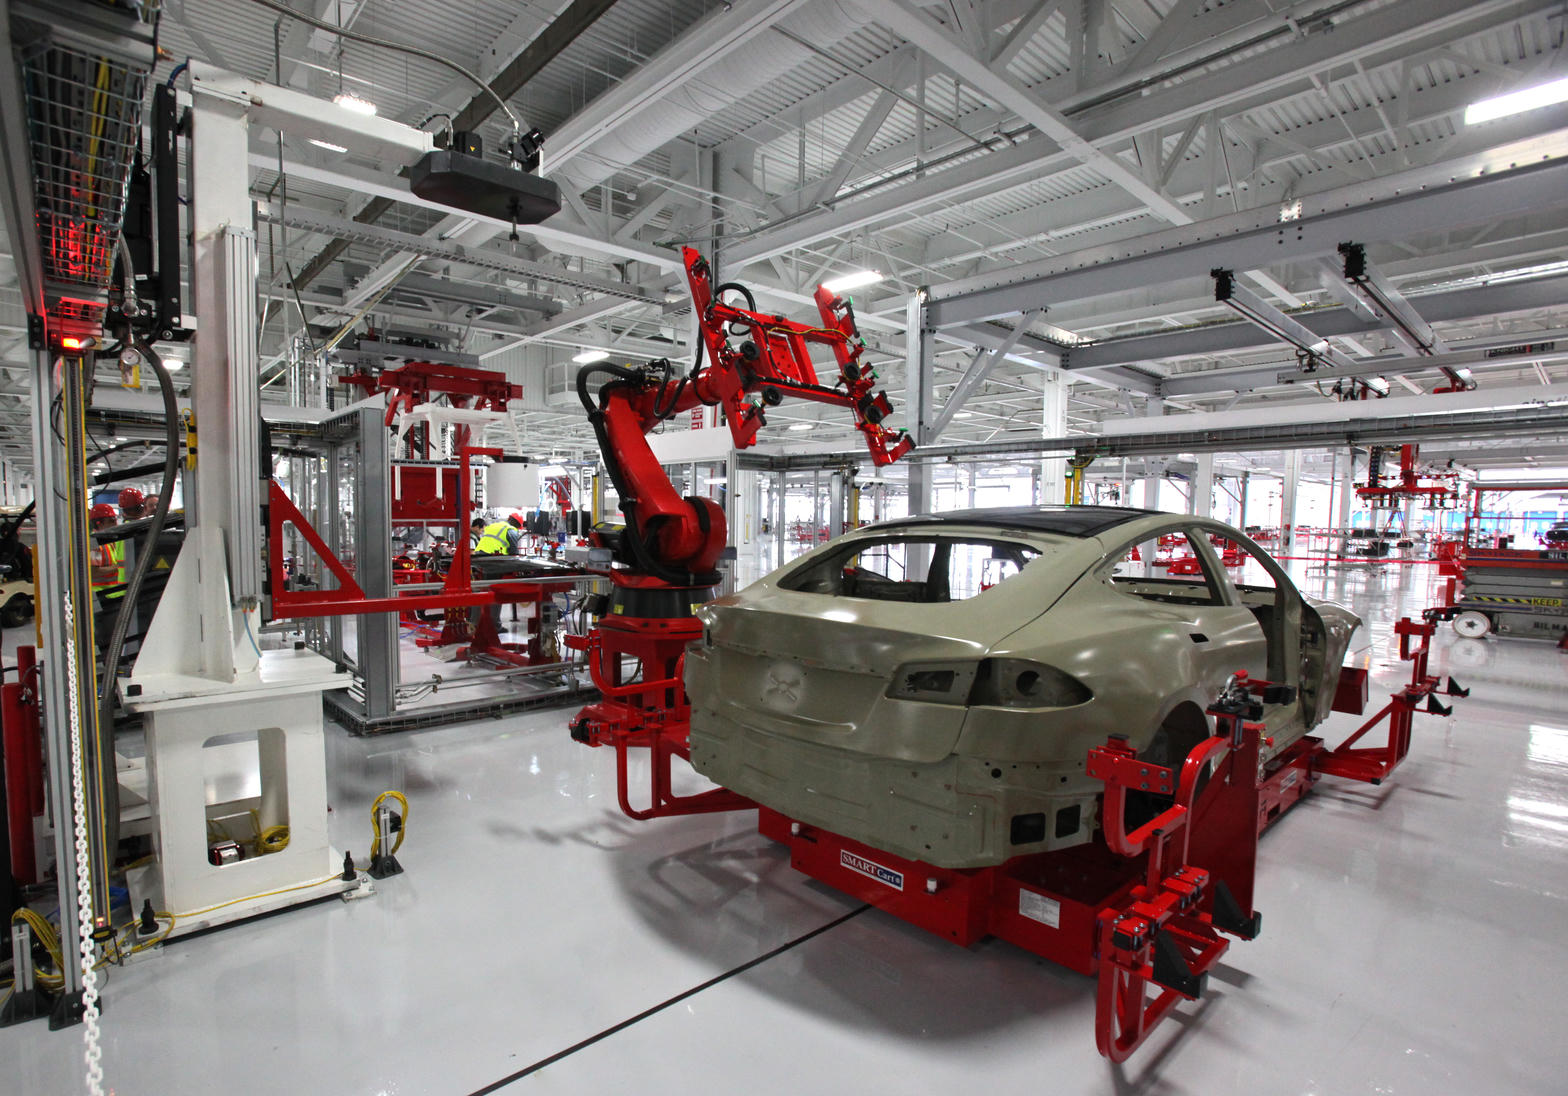
Fremont floor. A factory doing robots is already a shared-labor story.
Employee / talent sharing
Public commentary and S-1 Tesla mentions (87×) describe overlapping staff, shops, and compute.
The SpaceX S-1’s Tesla mentions (cited 87×) and public commentary describe overlapping staff, shops, and compute. Optimus as Mars labor, Tesla energy at Starbase, Starlink in the cab — the bodies already commute. Talent sharing without a merger is a gift of Tesla-trained labor into a launch co, or the reverse. Fremont converting S/X into an Optimus Academy is the labor tell: the factory is already a crossover.
Who pays
The company whose option pool trained the engineer who now ships the other company’s stack.
Board overlap
Same CEO, overlapping fiduciaries. An independent Tesla committee is the only collar that holds up in court.
Same CEO. Overlapping fiduciaries. Texas 2/3 vote helps Elon; a 3% bloc to wage war is ~$45B at a $1.5T Tesla. The only collar that holds up in court is an independent Tesla committee with its own bankers, its own model, and the power to say no. Anything short of that is a rubber stamp with a letterhead. The merge model’s independentCommittee toggle defaults false because it has not shipped.
Who pays
Tesla holders if the committee is captured. Elon if a real committee prices SpaceX as a launch co, not as a meme-AI wrapper.
A wafer. Terafab is a cited bill and a name in a bio — not this.
Terafab bill
~$55B-class chip moonshot. Neither wants it alone — which is an argument to merge, and also an argument that Tesla holders fund a fab for SpaceX sats.
Cited ~$55B-class captive node. Neither company wants that bill alone — which is the merge argument, and also the conflict. Tesla cash (~$43–45B pile) funding a fab whose first customers are Tesla inference and SpaceX AI sats is not arm’s length. Score it 8% complete, merge relevance 98. A letter of intent is not wafer starts. CHIPS, CFIUS, talent, and transfer pricing are the real gates.
Who pays
Tesla cash if the merger happens before Starship is a business. SpaceX if they try to eat $55B without Tesla’s P&L.
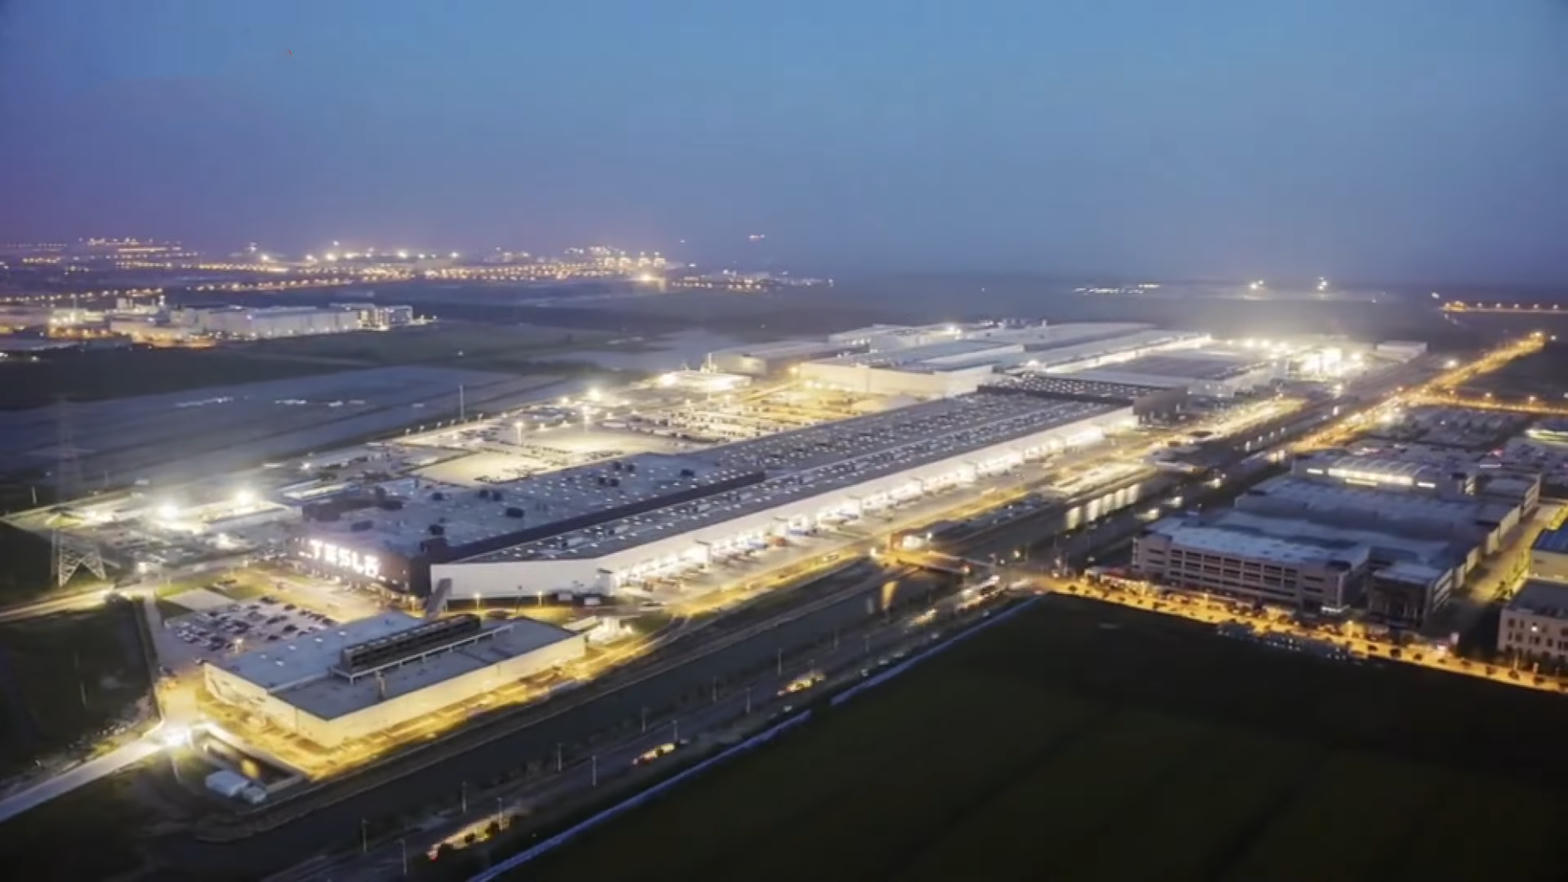
Giga Shanghai. Tesla’s largest factory does not share a regulator with Starshield.
China vs Starshield
Tesla’s largest factory and a US national-security launch/comm company do not share a regulator. This is not a footnote.
Tesla’s volume factory sits in Shanghai. SpaceX’s identity is US national security — Starshield, NSSL, classified customers. They do not share a regulator. CFIUS-class review in Washington and Party-class review in Beijing can each say no, or say yes-with-conditions that wreck the synergy slide. This is the silent killer. Do not bury it under “regulatory path.” Staffers read this file first.
Who pays
The combined company, in delay. Tesla if Beijing squeezes Giga Shanghai to punish a US defense merge. SpaceX if CFIUS forces a Starshield carve-out.
Pay-package overlay
Which trenches unlock Tesla compensation — and where that diverges from minority holders.
In trenches
20 million Tesla vehicles delivered
10M printed Jul 2026. Halfway as a count, not as a date.
Far
10 million active FSD subscriptions
1.48M in Q2 2026. Supervised, not unsupervised.
Demo-plus-internal
1 million bots delivered
Academy units ≠ delivered labor product.
Pilot
1 million commercial robotaxis
Dozens of vehicles. The tranche is the incentive; the fleet is not.