TRENCHES is a forensic operating system for Tesla and SpaceX objectives. Percentages are estimates from public artifacts — Master Plans, earnings, S-1s, FAA/FCC, NASA, trackers — not official KPIs. If something is a demo, it is labeled a demo. If a date moved, the old date is crossed out.
A merger module is game theory, not fanfic. Elon sits on both sides of the table. China is the silent killer. Combining them “might make Elon’s life a little easier.” That is the honest executive reason.
Each trench that can stall the scoreboard. These are the files that kill a window — not a probability of merger.
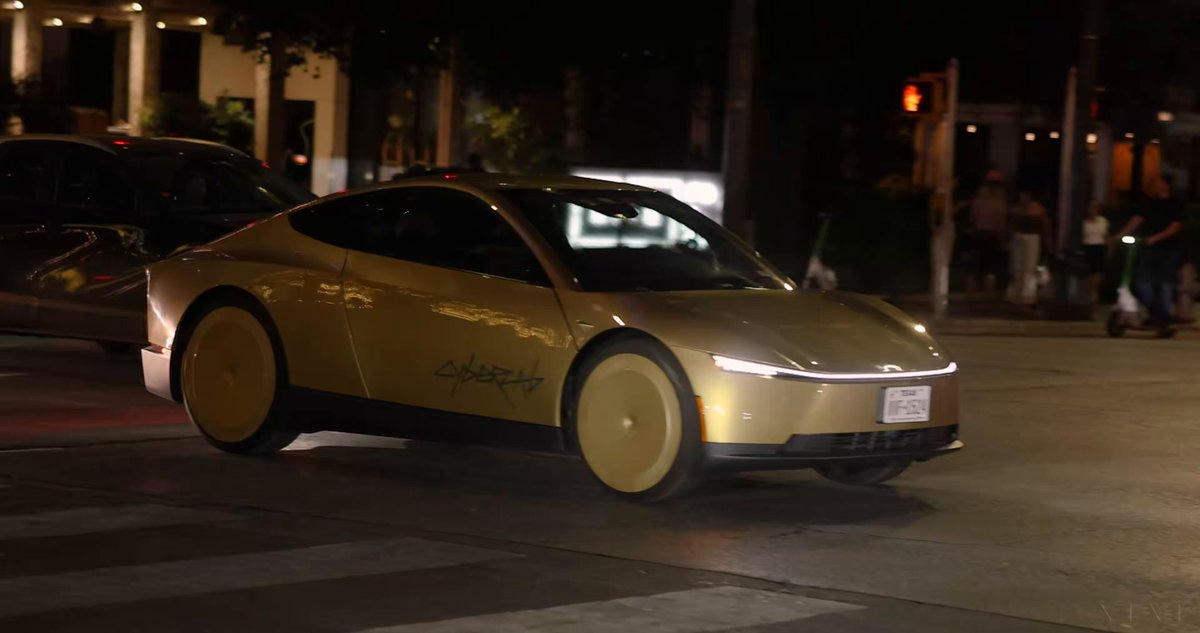
Cybercab on public pavement. This is the unsupervised product NHTSA actually regulates.
NHTSA FSD / robotaxi audits
highteslaOpen
A single unsupervised fatality can freeze the robotaxi trench and the merge clock.
FSD Supervised is a paid driver-responsibility product (~1.48M subs in Q2 2026). Unsupervised robotaxi is a geofenced paid pilot — low-million cumulative miles, dozens of Cybercabs, not Waymo-scale. NHTSA already has recall and investigation machinery on Autopilot/FSD. A fatality in a no-steering-wheel vehicle is not a press cycle. It freezes the robotaxi trench, the 1M-commercial-robotaxi pay tranche, and the merge model that assumes unit economics in Tesla segment reporting.
Trigger
Unsupervised fatality, or a broad FSD recall that puts a supervisor back in every paid mile.
Merge hit
Robotaxi-economics gauge drops. Window slides later. The 1M-robotaxi pay tranche becomes political poison.
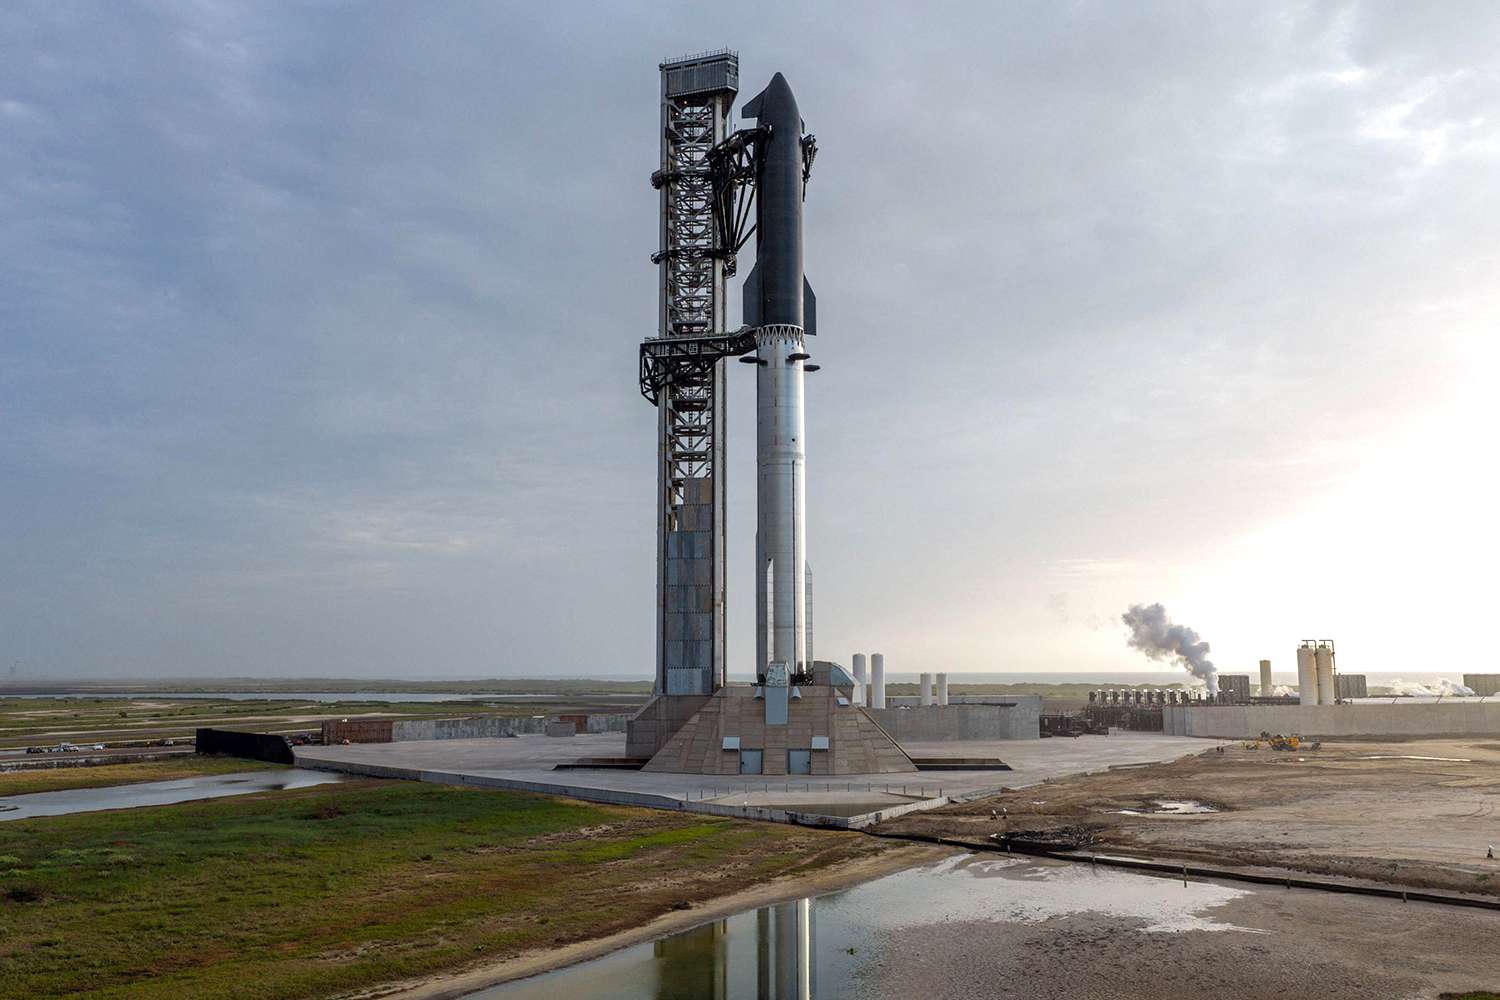
Starship on the pad at Starbase. Cadence is a license, not a photograph.
FAA Starship licenses / mishap clocks
highspacexOpen
Every anomaly inserts months. Cadence is a regulatory product as much as an engineering one.
Starship is licensed flight-by-flight. Flight 14 (Sep 2026) deployed 26 V3 Starlink sats and ended early on an engine. Flight 15 is a November attempt to catch the ship and the booster. A simulation of chopsticks is not a cadence. Until orbital reuse is boring, “Starship operational” stays a scenario toggle, not a fact.
Trigger
Mishap that opens a long investigation, or a license narrower than the flight manifesto.
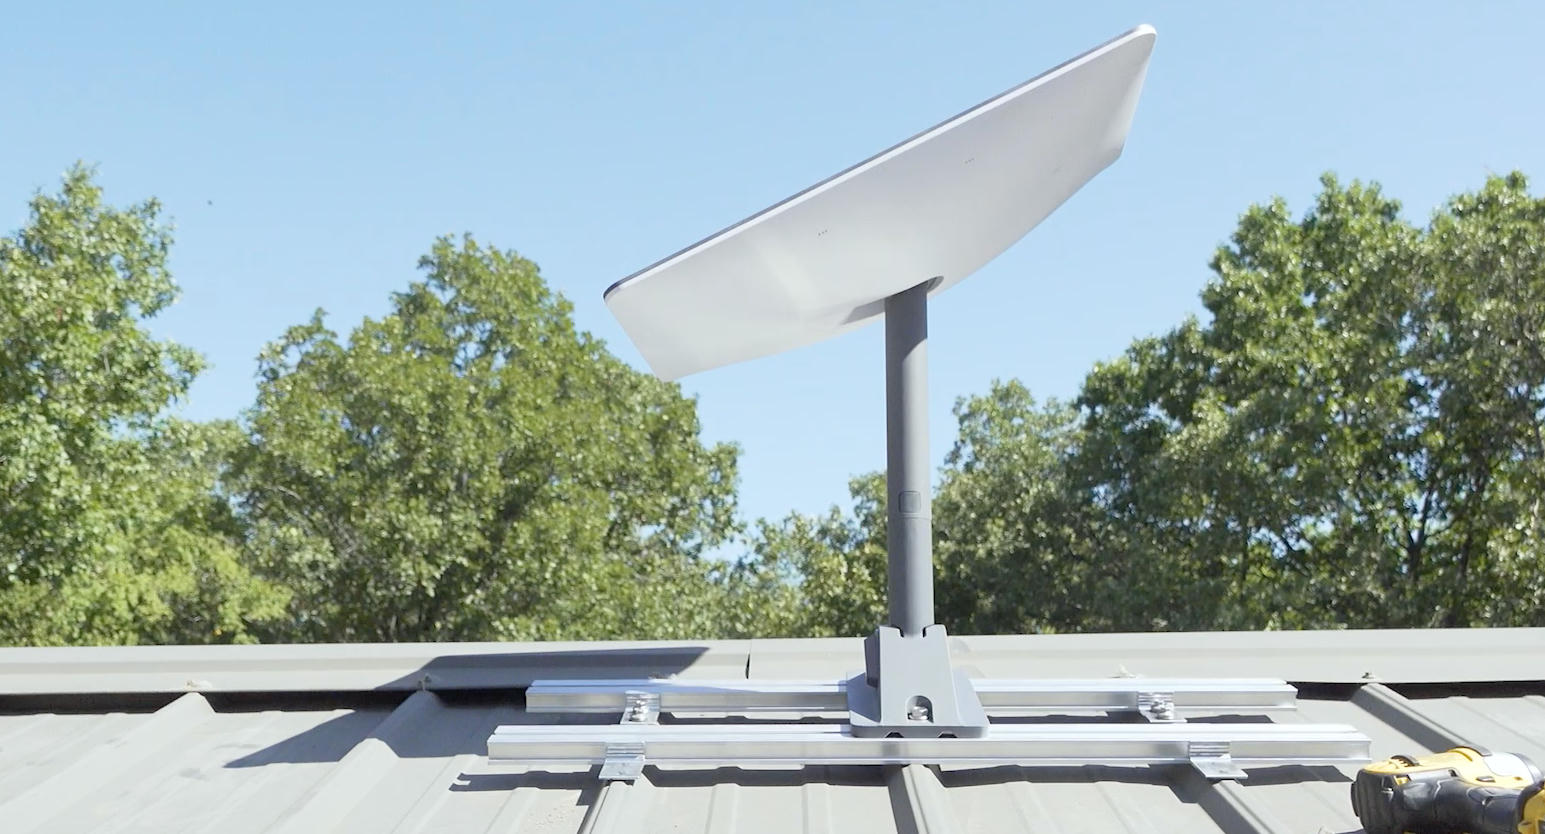
A working dish is not an authorized mega-constellation.
FCC Starlink shells + V3 constellation
medspacexOpen
Working product ≠ authorized mega-constellation. V3 100k request is a separate proceeding.
~12.9k launched / ~11.1k working (Sep 2026) is a live network. It is not an authorized mega-constellation. V3 and the 100k-class request sit in a separate FCC proceeding from today’s shells. Astronomers, debris dockets, and Kuiper all file in the same building. A dish on a roof proves service; it does not prove spectrum forever. Starlink-in-cab and AI-sat offtake for Terafab both assume the network keeps growing.
Trigger
Denial or severe condition on V3 / Gen2 shells; sharing rules that cap capacity.
Merge hit
Starlink-in-cab and the AI-sat demand story for Terafab both weaken.
Falcon 9 at a national-security pad. Starshield lives in this universe, not Shanghai’s.
ITAR / export on Starship, Raptor, Starshield
highspacexStructural
Makes a combined Tesla-in-China / SpaceX-as-defense-prime company a jurisdictional pretzel.
Starship, Raptor, and Starshield are defense-adjacent, export-controlled articles. Tesla’s supply chain, over-the-air software, and Giga Shanghai sit in a different export universe. Combining them is not paperwork — it is a pretzel: ITAR on the rocket, dual-use AI in the car, China volume in the factory. Staffers who own Starshield will not share a parent with Shanghai without a carve-out, a proxy board, or a no.
Trigger
Export determination that taints Tesla software/AI, or a Starshield program that cannot live inside a China-exposed parent.
Merge hit
Forces a carve-out that kills the “one company” slide.
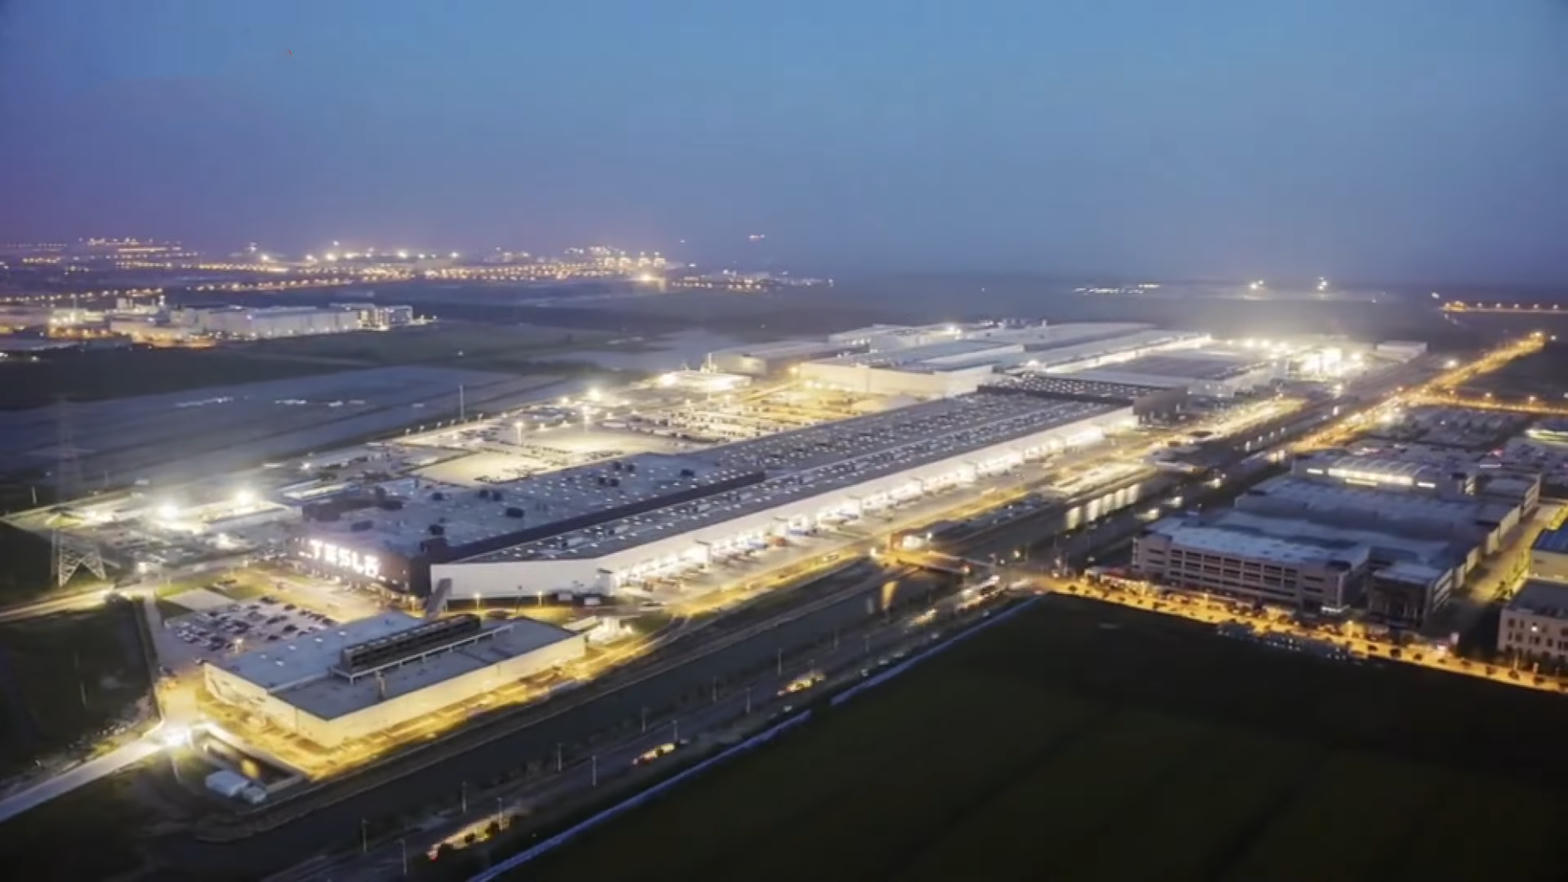
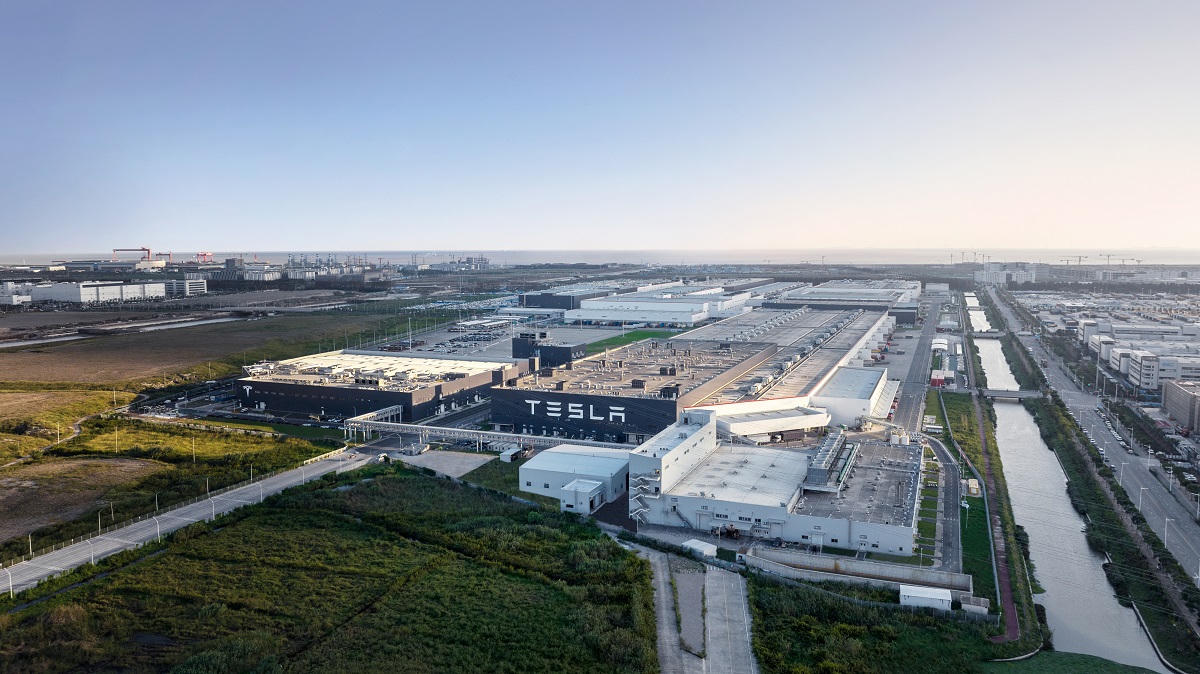
Giga Shanghai at night — Tesla’s volume factory, and the silent killer of a combined co.
China: Giga Shanghai vs Starshield identity
existentialbothSilent killer
CFIUS-class and Beijing-class reviews can stall a merger for years. Do not bury this.
Tesla’s largest factory and a large slice of deliveries sit in Shanghai, under Beijing. SpaceX is a US national-security launch and comms company. Combining them is not a Delaware filing. It is a CFIUS-class file in Washington and a Party-class file in Beijing. Either capital can stall a merger for years, or bless it with conditions that make the synergy slide a carcass. The merge model defaults chinaApproval to false for a reason.
Trigger
Beijing signal, a CFIUS letter, or a forced Starshield / Shanghai structural demand.
Merge hit
Regulatory gauge collapses. Base window becomes “not this decade” unless a carve-out is accepted.
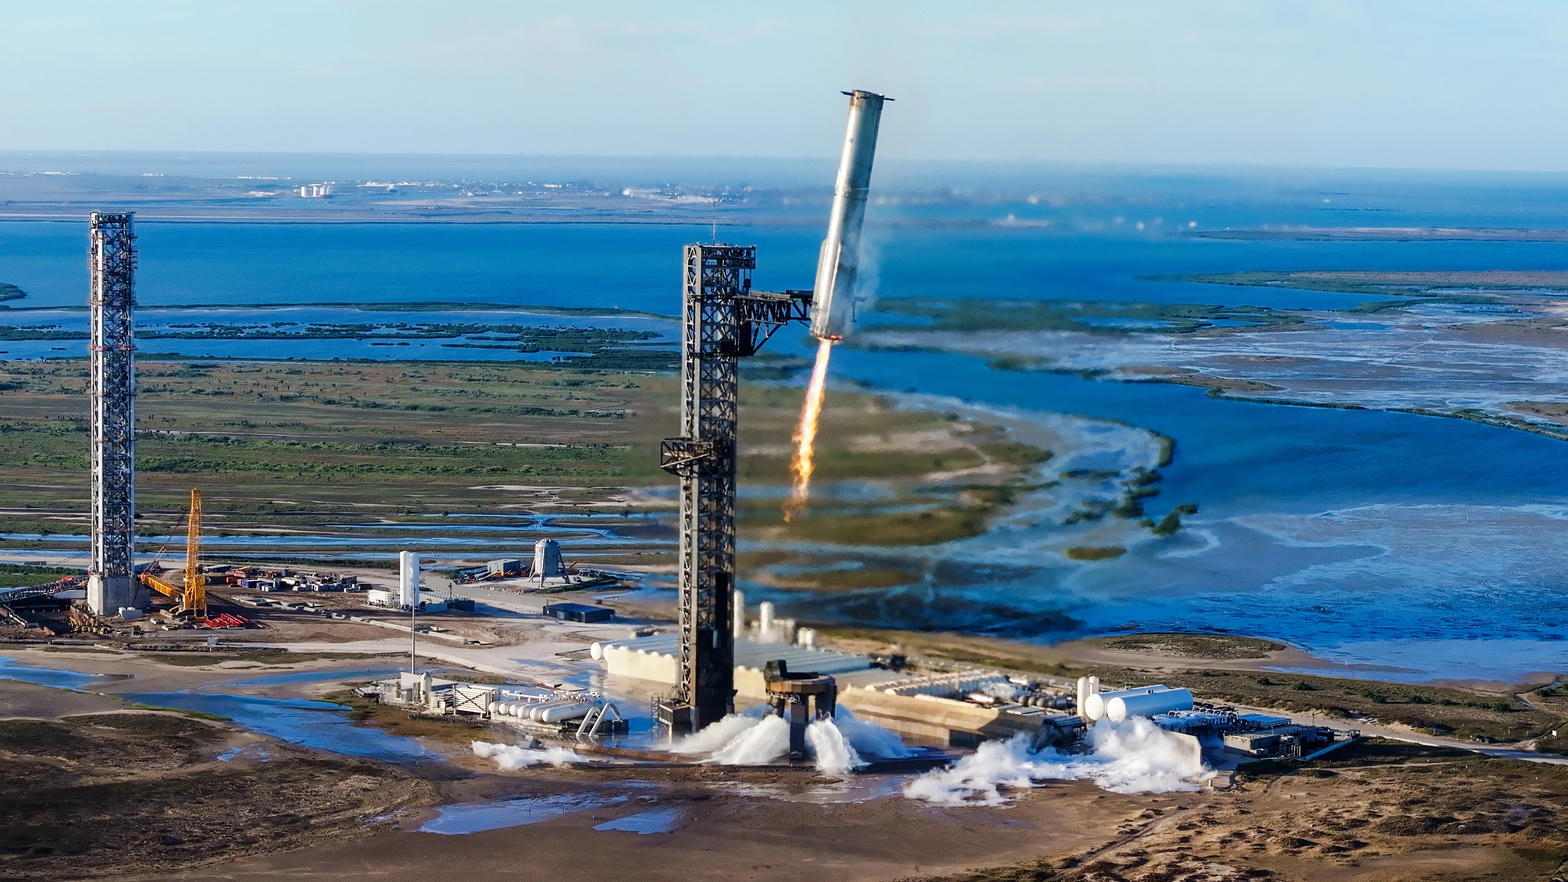
Mechazilla catch. Physical risk that writes the next mishap clock.
Pad explosions / environmental at Starbase
medspacexRecurring
Physical risk that also feeds the FAA clock.
Starbase is a factory, a pad, and a town. Catching Super Heavy is real; so are explosions, environmental challenges, and the license docket they feed. Physical risk in Cameron County is political risk in the FAA file. A catch photo is not airline-like reuse. Ship catch is delayed. The orbital site has to survive its own test program.
Trigger
Pad-destroying anomaly, or an environmental injunction that idles the orbital site.
Merge hit
Same as FAA — cadence dies, operational-orbit toggle stays off.
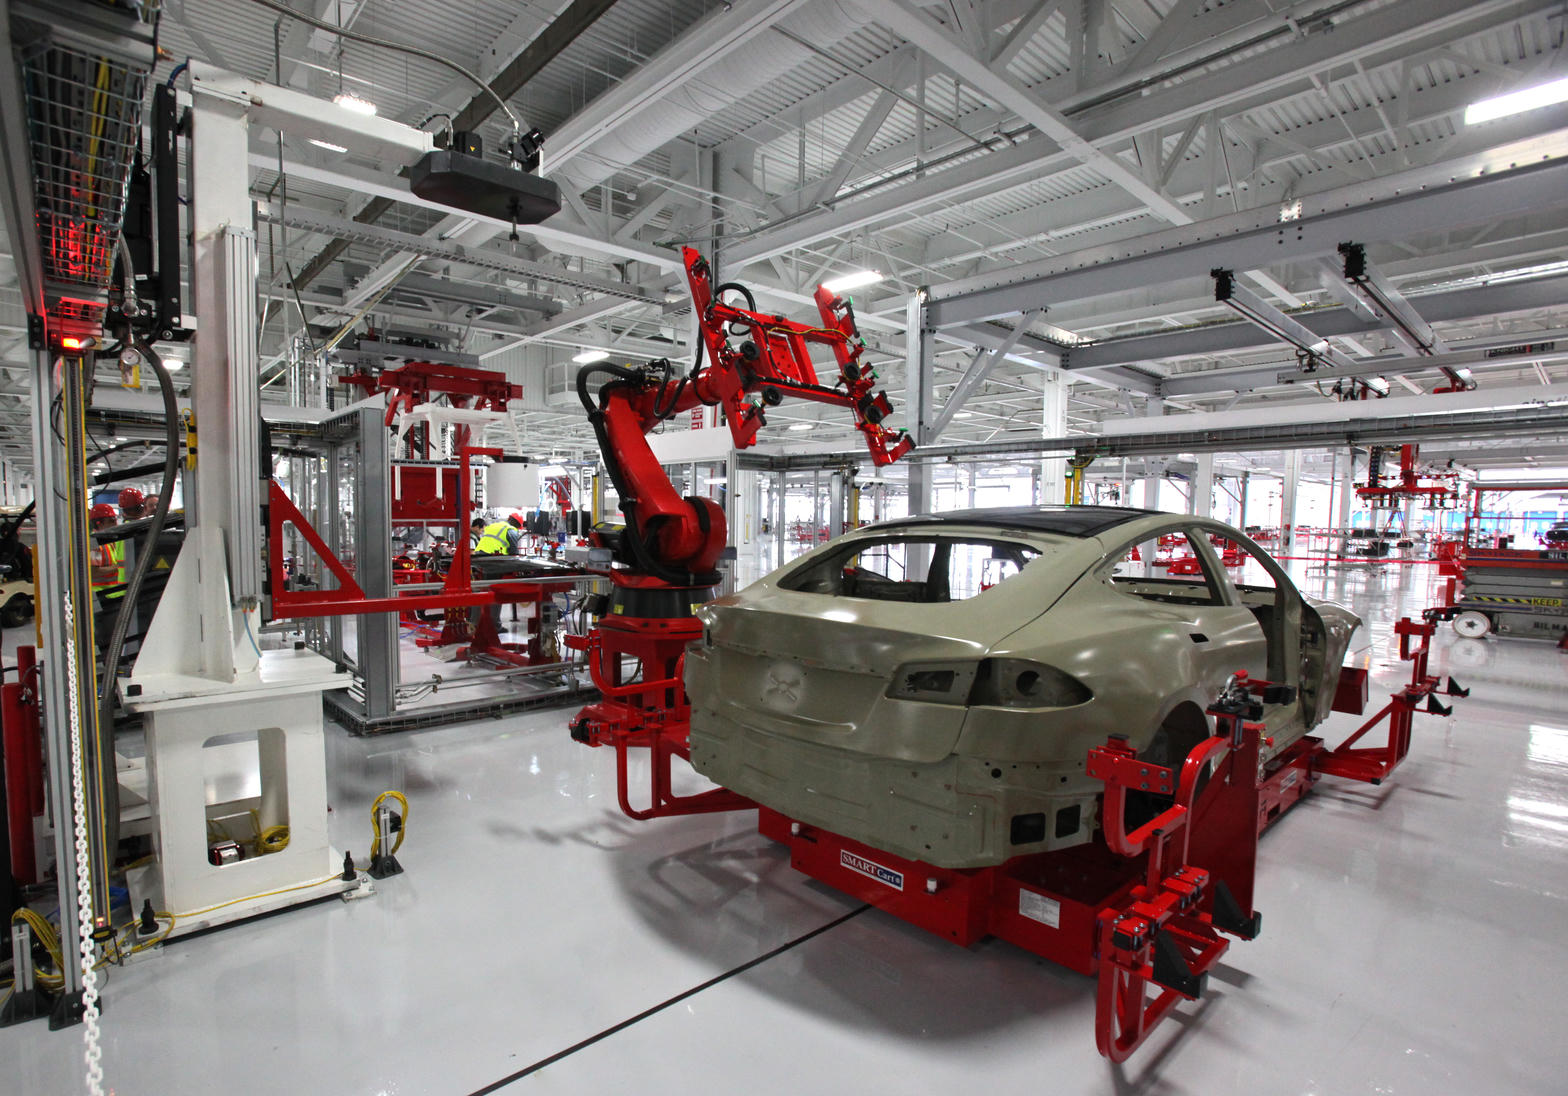
Fremont floor. S/X capacity being mined for Optimus Academy — labor is already a crossover.
Labor / UAW / Fremont conversion optics
medteslaWatch
S/X line converted to Optimus Academy. A factory doing robots is a labor story.
Fremont S/X converted toward Optimus Academy (~late Aug 2026). A factory that printed halo cars now prints humanoid R&D. “Design capacity 1M Optimus” is a slide. A labor product is headcount, safety, and a wage story. UAW and California optics travel with that conversion. Academy units are not delivered bots, and they are not a closed labor file.
Trigger
Organizing win, a fatal factory incident, or a conversion that reads as a jobs wipe.
Merge hit
Soft. Hurts Tesla narrative and the Optimus pay tranche more than the legal merge path.
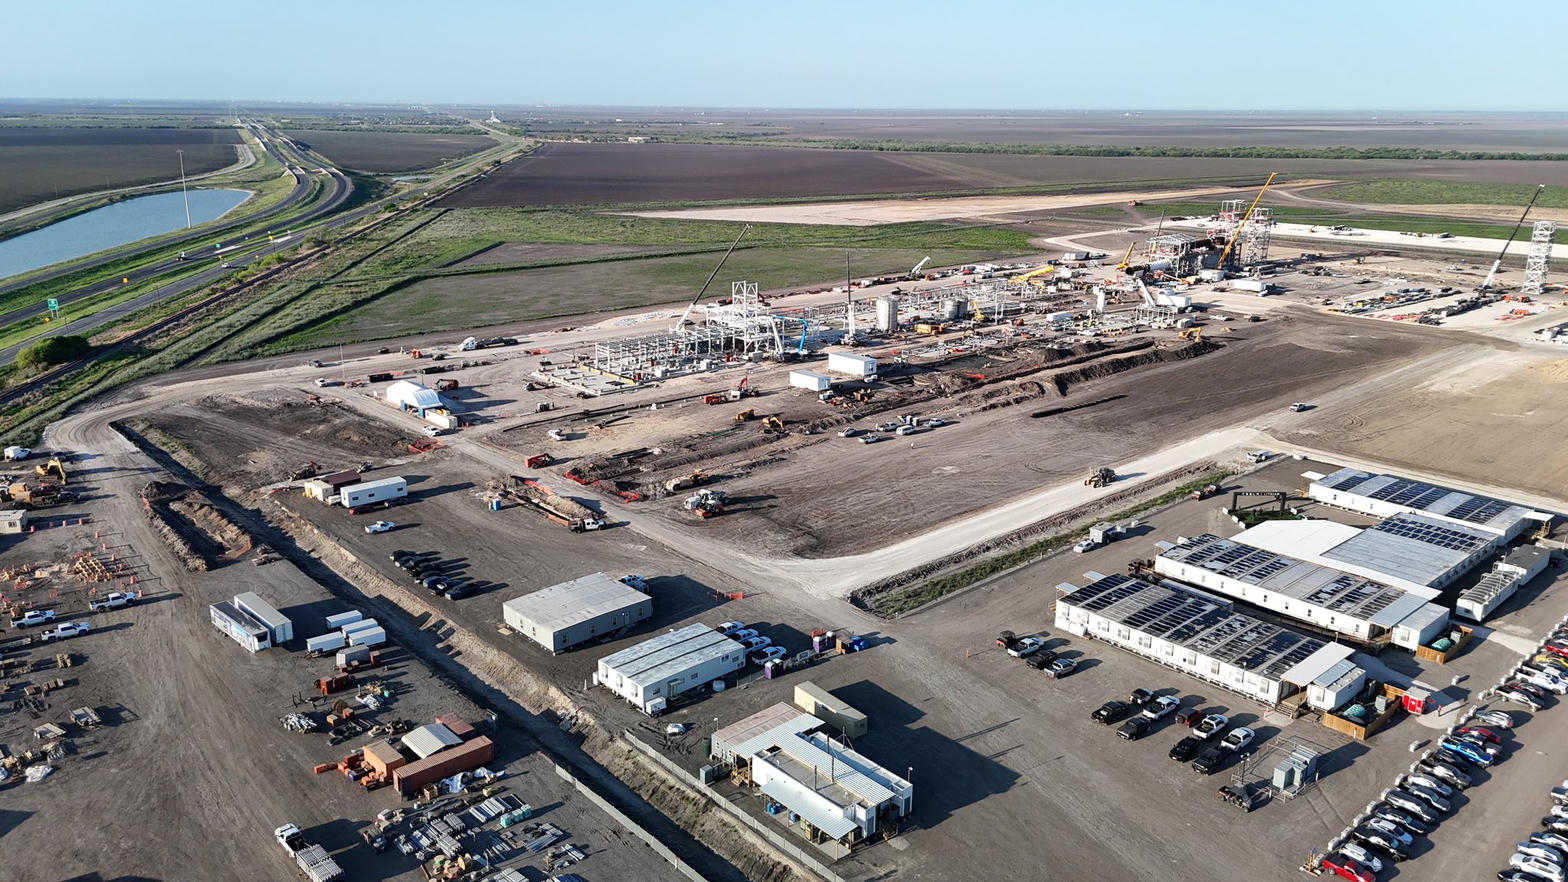
Tesla lithium refinery under construction. Dirt is not yield.
Lithium refinery / cathode ramp
medteslaRamp
Vertical materials 30–50%. A miss keeps Tesla a pack assembler.
The Corpus Christi-class lithium refinery is the vertical-materials trench. Public commentary puts independence in the 30–50% band. Construction is not nameplate; nameplate is not spec lithium in a qualified cathode. A miss keeps Tesla a pack assembler buying lithium and cathode at whoever’s price. Energy and robotaxi both sit on that bill.
Trigger
Ramp miss, environmental/permit stall, or cathode that does not qualify.
Merge hit
Tesla stays a car company with a materials bill. Weakens the industrial-champion merge story, not the legal one.
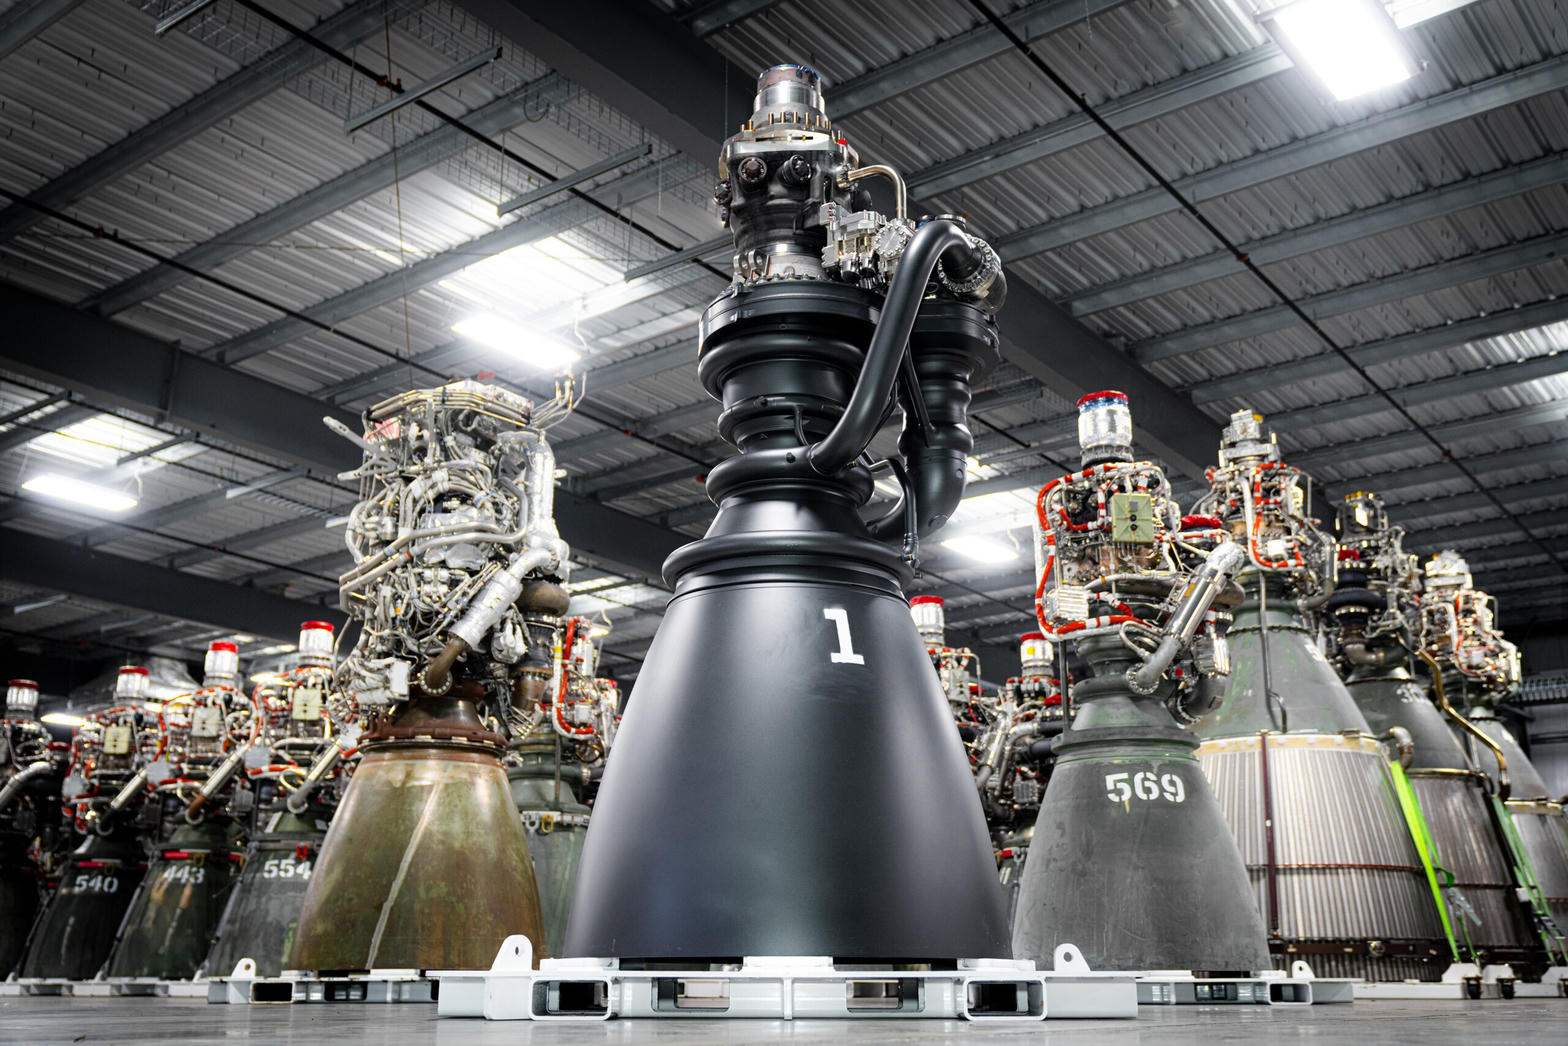
Engine cluster. Cadence is how many of these ship, not how they look.
Raptor yield
highspacexGate
Mars-window cadence is an engine factory problem wearing a rocket costume.
Flight rate, booster reuse, and ship-catch theater all sit on Raptor yield. A stacked engine photograph is not a production system. If engines are the constraint, Starship cannot be “operational” no matter what the pad looks like. Mars-window cadence is a factory problem wearing a rocket costume. Treat engine serial output as the gate, not the livestream.
Trigger
Yield stall, a design change that resets the line, or a flight that implicates the engine.
Merge hit
Engineering gauge and Starship-success scenario both freeze.
Giga Shanghai by day. The CFIUS file starts with this roof, not with a Delaware filing.
CFIUS / national-security review of a combined co
highbothIf merge
Starshield + Tesla China is the file the staffers actually read.
Separate from Beijing. A combined Tesla–SpaceX is a US company that owns a China auto factory and a national-security launch/comm business. Staffers read Starshield + Tesla China, not the synergy slide. Mitigation can mean a proxy board, a forced carve-out, or a no. Texas shareholder law does not bind CFIUS.
Trigger
Formal CFIUS notice, or a political demand to split Starshield before any vote.
Merge hit
Same file as China risk, Washington side. Regulatory gauge, not engineering.
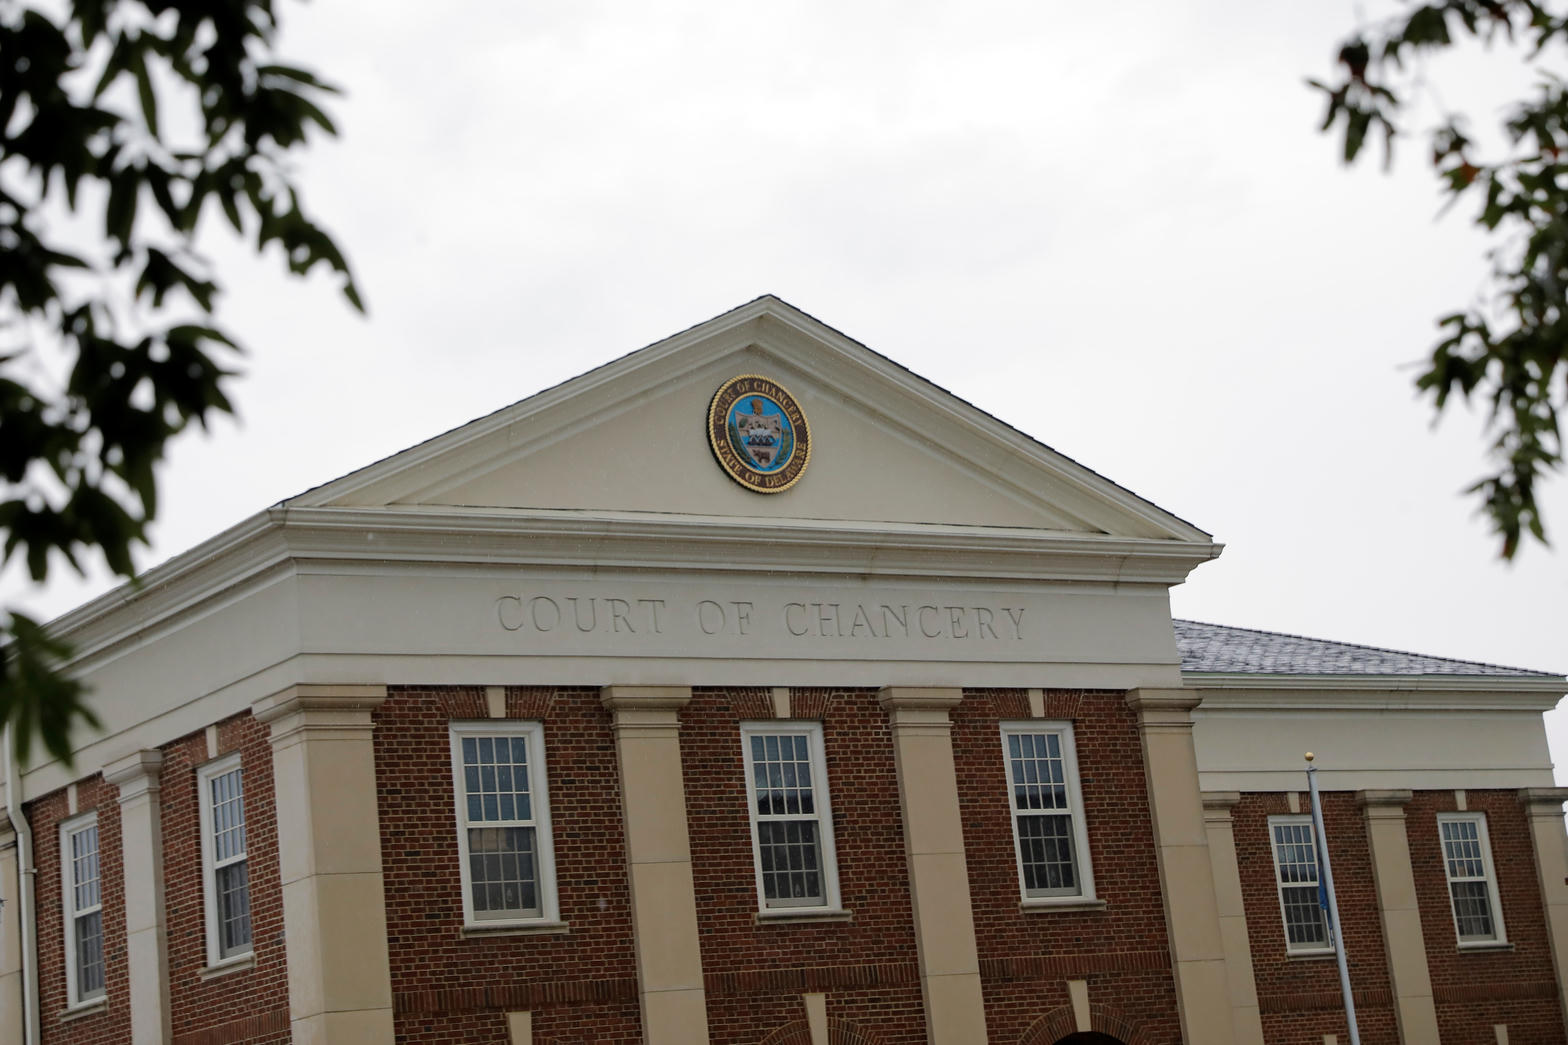
Delaware Court of Chancery. Related-party sales are the highest-scrutiny class.
Related-party Tesla–SpaceX–xAI traffic
highbothStructural
Framework agreement, $1B Tesla MTM on SpaceX, Grok in cars. Merger math is not arm’s length.
Framework agreement. Tesla’s Q2 2026 $1B mark-to-market on SpaceX holdings. Grok in cars after xAI collapsed into SpaceX pre-IPO. Overlapping shops and compute. Related-party traffic is already the fact pattern. A merger either collapses it into one P&L or cements a transfer-pricing swamp. Fairness opinions that ignore this are not fairness opinions.
Trigger
SEC or shareholder suit on related-party, or a disclosed offtake that prices Tesla as the captive customer.
Merge hit
Independent-committee toggle becomes mandatory. Without it the deal is indefensible.
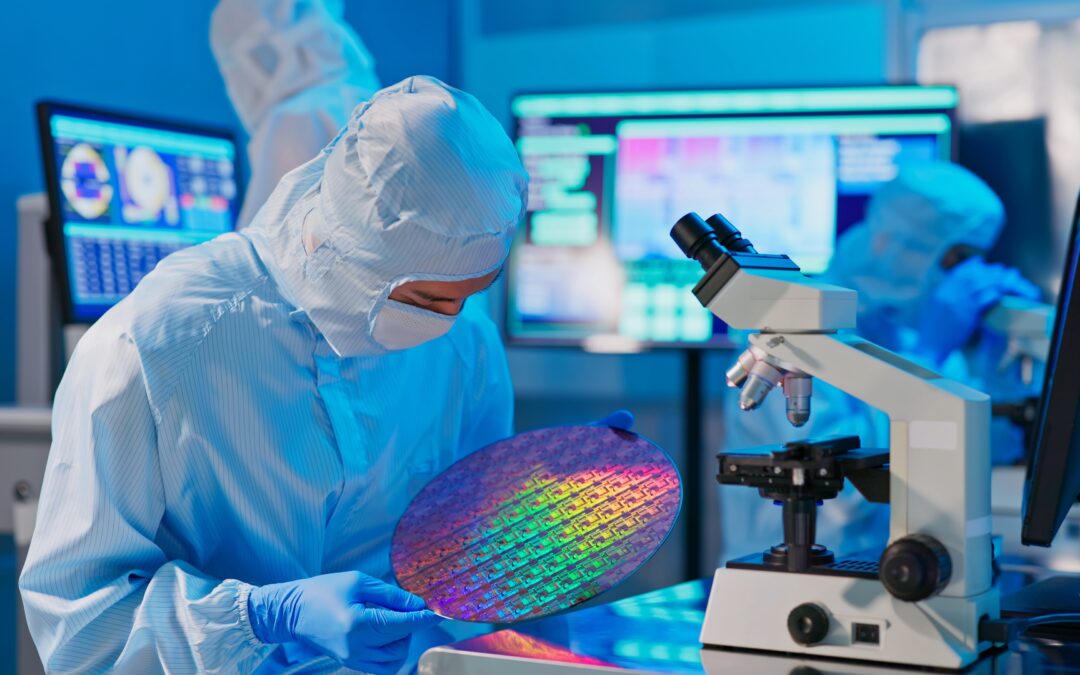
A wafer is what Terafab is not yet. Cited bill, no public yield.
Terafab $55B chip moonshot without a fab
highbothLOI
Highest merge-relevance node. A cited bill is not wafer starts. CHIPS/CFIUS and talent are the real gates.
Highest merge-relevance node in the set (98) at ~8% complete. Cited ~$55B-class captive node. Framework exists; projects still “subject to separate negotiations.” No public yield, no wafer starts as a Tesla/SpaceX plant. The conflict: Tesla holders funding a fab whose customers are Tesla inference and SpaceX AI sats. CHIPS, CFIUS, talent, and transfer pricing are the gates — not the name in a bio.
Trigger
LOI dies, or a real commitment that Tesla funds without a collar.
Merge hit
If it dies, the strongest merge argument dies with it. If it commits without a merger, Tesla holders fund SpaceX silicon.
2025 Tesla pay package vs minority holders
highteslaLive
1M Optimus + 1M commercial robotaxis can pull capital away from auto margin.
The live Tesla pay package pays Elon for printing 1M Optimus and 1M commercial robotaxis, among other tranches. Those numbers pull capex and attention away from auto margin. Delaware already voided a prior package. Texas law is friendlier; minority holders are not. A CEO maximizing his Tesla package is not maximizing a fair SpaceX exchange ratio. Academy units counted as “delivered” would be the tell.
Trigger
Lawsuit, withhold vote, or a tranche that is gamed (Academy units counted as delivered).
Merge hit
Makes the independent Tesla committee politically necessary. Package incentives ≠ minority-holder incentives.